


After a decade of product proliferation, cell interface
optimization, and the search for buyer acquisition, a number of the most
necessary aggressive questions are transferring under the display screen: who controls the
infrastructure, who carries the operational danger, and who might be trusted to
maintain the system working when the interface adjustments?
For a lot of the previous, monetary know-how was constructed round
unbundling, with specialised purposes promising a greater expertise for
buying and selling, saving, funds, or another finance-related companies. That mannequin
created real innovation and selection. However interface differentiation alone is
turning into more durable to maintain.
London’s buying and selling trade is coming residence!
Price strain, advanced tax environments, and rising
capital and working necessities throughout fragmented European markets are
making scale and operational depth extra necessary.
The European Fund and Asset Administration Affiliation (EFAMA)
reported that working revenue margins fell to 11.1 foundation factors of common AuM
in 2023, the bottom degree for the reason that 2008 monetary disaster. EFAMA attributed the
strain to persistent price erosion and rising prices, together with know-how
expenditure.
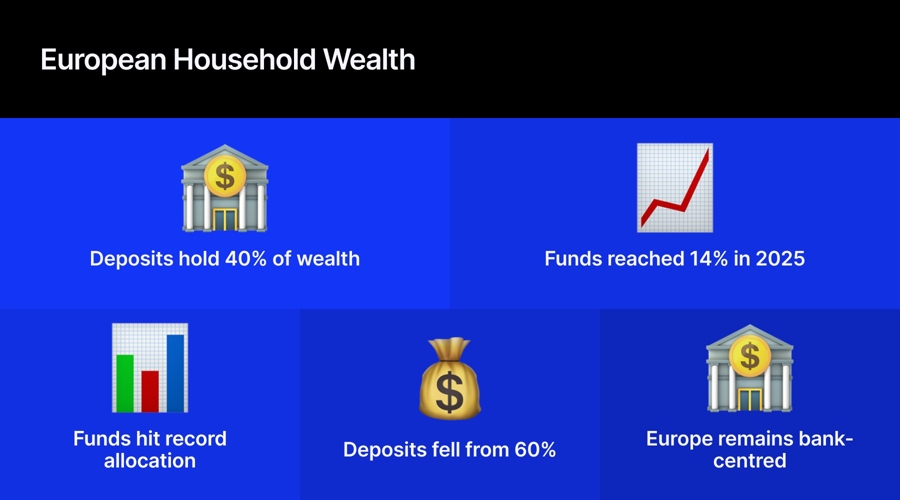
Europe begins from a definite monetary baseline outlined by
bank-centred wealth. In July 2026, EFAMA reported that European households
nonetheless held 40% of their monetary wealth in financial institution deposits, solely modestly under
the 42% peak reached in 2022 and better than the 37% degree seen in 2015.
That persistence displays the long-standing position of banks as
the first monetary relationship for European households. But family
allocations are steadily shifting: deposits accounted for 45% of latest monetary
acquisitions after 2020, down from 60% between 2015 and 2019, whereas
investment-fund holdings reached a file 14% of family property in 2025.
Coverage measures comparable to Financial savings and Funding Accounts
(SIAs), now applied throughout greater than a dozen European international locations, are designed
to speed up that transition, however the information recommend that the reallocation of
family wealth stays an evolutionary course of.
Integration With out Full Possession
Integration, nevertheless, doesn’t require one establishment to
personal each hyperlink within the chain. Open banking, specialist custody and clearing
Clearing
Clearing is a normal time period that merely means many alternative issues relying on the topic and associated trade. Mostly, this refers back to the reciprocal change between banks of checks and drafts, and the settlement of the variations, or the full of claims settled at a clearinghouse. In finance and banking, the phrase clearing has completely different meanings relying on the extra particular enterprise mannequin. Transferring checks from the financial institution the place they had been deposited to the financial institution on which they had been drawn. Th
Clearing is a normal time period that merely means many alternative issues relying on the topic and associated trade. Mostly, this refers back to the reciprocal change between banks of checks and drafts, and the settlement of the variations, or the full of claims settled at a clearinghouse. In finance and banking, the phrase clearing has completely different meanings relying on the extra particular enterprise mannequin. Transferring checks from the financial institution the place they had been deposited to the financial institution on which they had been drawn. Th
Learn this Time period,
embedded finance, and white-label infrastructure have made it attainable to
mix companies from completely different suppliers whereas presenting clients with a
unified expertise.
Vertical integration can supply higher management and
probably higher economics, however it additionally brings extra capital necessities,
regulatory accountability, and operational complexity.
Freedom24 supplies one instance of that trade-off, combining
centralized, digital-first Tradernet know-how and bodily infrastructure
with operations serving completely different European markets. The broader lesson is that
European scale more and more relies on know-how that may be centralized
with out turning into inflexible on the native degree.
When the Interface Turns into Programmable
The extra consequential shift is going on on the interface
itself. Open APIs, embedded finance, and programmatic buying and selling have already
separated elements of the client expertise from the establishment that gives
the underlying service. Synthetic
intelligence extends that separation.
Protocols such because the Mannequin Context Protocol (MCP) give AI
purposes an ordinary strategy to work with exterior information and instruments. Cellular
purposes aren’t going away; they continue to be necessary for onboarding,
id verification, and consumer relationships. However an app now not must be
the one door right into a monetary platform.
As conversational AI, automated portfolio instruments, and agentic
programs develop, a buyer could more and more categorical an funding intention
by means of one interface whereas one other establishment performs the underlying
monetary service. That creates a more durable strategic query: if the interface
can transfer, the place does the sturdy worth stay?
Within the first few weeks of agentic buying and selling on Robinhood, over 50,000 clients have opened agentic buying and selling accounts and are buying and selling tens of millions of {dollars} per day of equities and choices.
Writing and executing subtle methods or optimizing your on a regular basis spending now not…
— Vlad Tenev (@vladtenev) June 18, 2026
Infrastructure Is Not Sufficient
There’s a sturdy case for saying “infrastructure.” There may be
additionally a great cause to be cautious. Know-how historical past is stuffed with examples in
which the corporate closest to the client captured the economics whereas the
programs beneath grew to become more and more interchangeable.
Search, digital marketplaces, and elements of communications
all exhibit the ability of aggregation. An AI agent that may evaluate
suppliers, route transactions, and negotiate on behalf of a buyer might put
comparable strain on brokerage infrastructure.
The reply, then, can’t merely be that infrastructure wins.
Worth will stay the place substitution is tough.
In finance, that may imply regulated market entry, custody,
liquidity, financing, execution
Execution
Execution is the method throughout which a consumer submits an order to the brokerage, which consequently executes it leading to an open place in a given asset. The execution of the order happens solely when it’s stuffed. There may be sometimes a time delay between the location of the order and the execution which is named latency.Within the retail FX area, dependable brokers at all times try to ship greatest execution to their shoppers to be able to preserve a stable enterprise relationship with them. This can be a co
Execution is the method throughout which a consumer submits an order to the brokerage, which consequently executes it leading to an open place in a given asset. The execution of the order happens solely when it’s stuffed. There may be sometimes a time delay between the location of the order and the execution which is named latency.Within the retail FX area, dependable brokers at all times try to ship greatest execution to their shoppers to be able to preserve a stable enterprise relationship with them. This can be a co
Learn this Time period high quality, proprietary data, or the
skill to handle danger throughout jurisdictions. None of those benefits is
everlasting. However a supplier that mixes a number of of them could also be more durable to
substitute than one that provides little greater than connectivity.
A Broader Set of Capabilities
That additionally adjustments the economics. If software program brokers can
evaluate execution and transfer between suppliers, a primary transaction price turns into a
much less convincing moat.
Infrastructure suppliers might want to earn from a wider set
of capabilities, whether or not by means of custody, financing, securities lending,
international change, liquidity, information, or differentiated execution. The important thing
query just isn’t merely who owns the stability sheet or the licence, however who can
mix scarce capabilities in a type that different interfaces can really use.
The identical logic applies to establishments of very completely different
sizes. World custodians can depend on scale in post-trade infrastructure.
Specialist brokers and know-how suppliers could compete on market entry,
execution, distribution, or specific operational capabilities.
The European market is unlikely to break down right into a single
profitable mannequin; the extra attention-grabbing query is how these layers join and
which ones stay genuinely tough to interchange.
The Monetary Rails Could Additionally Change
The underlying rails could change as effectively. Tokenization and
distributed ledgers are already being
examined as alternate options to elements of the standard monetary stack.
In its April 2026 evaluation of tokenized money-market funds,
the European Central Financial institution recognized quicker settlement, near-24/7 availability,
and programmability as potential advantages whereas additionally highlighting liquidity and
operational dangers.
The know-how can change how the system works with out
eliminating the underlying jobs of authorization, settlement, liquidity, and
danger administration.
Rethinking Human Oversight
The rise of automated execution additionally adjustments what “human
oversight” must imply. An individual can’t fairly approve each routine
transaction in a high-speed system.
In a mature agentic structure, individuals would as a substitute
outline the authority below which software program can act: what the system is allowed
to do, inside what limits, and what occasions require escalation or intervention.
That’s broadly in keeping with the human-oversight strategy
in Article 14 of the EU AI Act, which emphasizes proportionate safeguards and
deployer controls somewhat than steady guide intervention.
Governance Strikes Into the System
Governance due to this fact strikes nearer to the equipment of
finance itself. Authorized guidelines, compliance necessities, and danger limits
more and more need to be translated into system permissions, API controls,
monitoring, and transaction data that may be reconstructed after the actual fact.
The 2026 Oxford–GlobeScan survey illustrates why this
issues past know-how groups: geoeconomic danger ranked first amongst
respondents at 76%, whereas AI and know-how danger rose from 17% in 2025 to 44%,
and governance reached 45% amongst ESG-related reputational considerations.
The Combat Beneath the Interface
The attention-grabbing battle won’t be between an app and an API.
It is going to be over what sits beneath each.
If an AI agent can select amongst monetary suppliers, the
suppliers greatest positioned to retain worth shall be those who nonetheless supply
one thing the agent can’t deal with as interchangeable: dependable market entry,
execution, regulated custody, financing, information, core know-how and supply
stack, or a mix of them.
On the finish of the day, the interface could or could not
basically change, and as soon as extra once more after that. The underlying take a look at is
whether or not the establishment stays helpful when the client now not has to
enter by means of its entrance door.
After a decade of product proliferation, cell interface
optimization, and the search for buyer acquisition, a number of the most
necessary aggressive questions are transferring under the display screen: who controls the
infrastructure, who carries the operational danger, and who might be trusted to
maintain the system working when the interface adjustments?
For a lot of the previous, monetary know-how was constructed round
unbundling, with specialised purposes promising a greater expertise for
buying and selling, saving, funds, or another finance-related companies. That mannequin
created real innovation and selection. However interface differentiation alone is
turning into more durable to maintain.
London’s buying and selling trade is coming residence!
Price strain, advanced tax environments, and rising
capital and working necessities throughout fragmented European markets are
making scale and operational depth extra necessary.
The European Fund and Asset Administration Affiliation (EFAMA)
reported that working revenue margins fell to 11.1 foundation factors of common AuM
in 2023, the bottom degree for the reason that 2008 monetary disaster. EFAMA attributed the
strain to persistent price erosion and rising prices, together with know-how
expenditure.
Europe begins from a definite monetary baseline outlined by
bank-centred wealth. In July 2026, EFAMA reported that European households
nonetheless held 40% of their monetary wealth in financial institution deposits, solely modestly under
the 42% peak reached in 2022 and better than the 37% degree seen in 2015.
That persistence displays the long-standing position of banks as
the first monetary relationship for European households. But family
allocations are steadily shifting: deposits accounted for 45% of latest monetary
acquisitions after 2020, down from 60% between 2015 and 2019, whereas
investment-fund holdings reached a file 14% of family property in 2025.
Coverage measures comparable to Financial savings and Funding Accounts
(SIAs), now applied throughout greater than a dozen European international locations, are designed
to speed up that transition, however the information recommend that the reallocation of
family wealth stays an evolutionary course of.
Integration With out Full Possession
Integration, nevertheless, doesn’t require one establishment to
personal each hyperlink within the chain. Open banking, specialist custody and clearing
Clearing
Clearing is a normal time period that merely means many alternative issues relying on the topic and associated trade. Mostly, this refers back to the reciprocal change between banks of checks and drafts, and the settlement of the variations, or the full of claims settled at a clearinghouse. In finance and banking, the phrase clearing has completely different meanings relying on the extra particular enterprise mannequin. Transferring checks from the financial institution the place they had been deposited to the financial institution on which they had been drawn. Th
Clearing is a normal time period that merely means many alternative issues relying on the topic and associated trade. Mostly, this refers back to the reciprocal change between banks of checks and drafts, and the settlement of the variations, or the full of claims settled at a clearinghouse. In finance and banking, the phrase clearing has completely different meanings relying on the extra particular enterprise mannequin. Transferring checks from the financial institution the place they had been deposited to the financial institution on which they had been drawn. Th
Learn this Time period,
embedded finance, and white-label infrastructure have made it attainable to
mix companies from completely different suppliers whereas presenting clients with a
unified expertise.
Vertical integration can supply higher management and
probably higher economics, however it additionally brings extra capital necessities,
regulatory accountability, and operational complexity.
Freedom24 supplies one instance of that trade-off, combining
centralized, digital-first Tradernet know-how and bodily infrastructure
with operations serving completely different European markets. The broader lesson is that
European scale more and more relies on know-how that may be centralized
with out turning into inflexible on the native degree.
When the Interface Turns into Programmable
The extra consequential shift is going on on the interface
itself. Open APIs, embedded finance, and programmatic buying and selling have already
separated elements of the client expertise from the establishment that gives
the underlying service. Synthetic
intelligence extends that separation.
Protocols such because the Mannequin Context Protocol (MCP) give AI
purposes an ordinary strategy to work with exterior information and instruments. Cellular
purposes aren’t going away; they continue to be necessary for onboarding,
id verification, and consumer relationships. However an app now not must be
the one door right into a monetary platform.
As conversational AI, automated portfolio instruments, and agentic
programs develop, a buyer could more and more categorical an funding intention
by means of one interface whereas one other establishment performs the underlying
monetary service. That creates a more durable strategic query: if the interface
can transfer, the place does the sturdy worth stay?
Within the first few weeks of agentic buying and selling on Robinhood, over 50,000 clients have opened agentic buying and selling accounts and are buying and selling tens of millions of {dollars} per day of equities and choices.
Writing and executing subtle methods or optimizing your on a regular basis spending now not…
— Vlad Tenev (@vladtenev) June 18, 2026
Infrastructure Is Not Sufficient
There’s a sturdy case for saying “infrastructure.” There may be
additionally a great cause to be cautious. Know-how historical past is stuffed with examples in
which the corporate closest to the client captured the economics whereas the
programs beneath grew to become more and more interchangeable.
Search, digital marketplaces, and elements of communications
all exhibit the ability of aggregation. An AI agent that may evaluate
suppliers, route transactions, and negotiate on behalf of a buyer might put
comparable strain on brokerage infrastructure.
The reply, then, can’t merely be that infrastructure wins.
Worth will stay the place substitution is tough.
In finance, that may imply regulated market entry, custody,
liquidity, financing, execution
Execution
Execution is the method throughout which a consumer submits an order to the brokerage, which consequently executes it leading to an open place in a given asset. The execution of the order happens solely when it’s stuffed. There may be sometimes a time delay between the location of the order and the execution which is named latency.Within the retail FX area, dependable brokers at all times try to ship greatest execution to their shoppers to be able to preserve a stable enterprise relationship with them. This can be a co
Execution is the method throughout which a consumer submits an order to the brokerage, which consequently executes it leading to an open place in a given asset. The execution of the order happens solely when it’s stuffed. There may be sometimes a time delay between the location of the order and the execution which is named latency.Within the retail FX area, dependable brokers at all times try to ship greatest execution to their shoppers to be able to preserve a stable enterprise relationship with them. This can be a co
Learn this Time period high quality, proprietary data, or the
skill to handle danger throughout jurisdictions. None of those benefits is
everlasting. However a supplier that mixes a number of of them could also be more durable to
substitute than one that provides little greater than connectivity.
A Broader Set of Capabilities
That additionally adjustments the economics. If software program brokers can
evaluate execution and transfer between suppliers, a primary transaction price turns into a
much less convincing moat.
Infrastructure suppliers might want to earn from a wider set
of capabilities, whether or not by means of custody, financing, securities lending,
international change, liquidity, information, or differentiated execution. The important thing
query just isn’t merely who owns the stability sheet or the licence, however who can
mix scarce capabilities in a type that different interfaces can really use.
The identical logic applies to establishments of very completely different
sizes. World custodians can depend on scale in post-trade infrastructure.
Specialist brokers and know-how suppliers could compete on market entry,
execution, distribution, or specific operational capabilities.
The European market is unlikely to break down right into a single
profitable mannequin; the extra attention-grabbing query is how these layers join and
which ones stay genuinely tough to interchange.
The Monetary Rails Could Additionally Change
The underlying rails could change as effectively. Tokenization and
distributed ledgers are already being
examined as alternate options to elements of the standard monetary stack.
In its April 2026 evaluation of tokenized money-market funds,
the European Central Financial institution recognized quicker settlement, near-24/7 availability,
and programmability as potential advantages whereas additionally highlighting liquidity and
operational dangers.
The know-how can change how the system works with out
eliminating the underlying jobs of authorization, settlement, liquidity, and
danger administration.
Rethinking Human Oversight
The rise of automated execution additionally adjustments what “human
oversight” must imply. An individual can’t fairly approve each routine
transaction in a high-speed system.
In a mature agentic structure, individuals would as a substitute
outline the authority below which software program can act: what the system is allowed
to do, inside what limits, and what occasions require escalation or intervention.
That’s broadly in keeping with the human-oversight strategy
in Article 14 of the EU AI Act, which emphasizes proportionate safeguards and
deployer controls somewhat than steady guide intervention.
Governance Strikes Into the System
Governance due to this fact strikes nearer to the equipment of
finance itself. Authorized guidelines, compliance necessities, and danger limits
more and more need to be translated into system permissions, API controls,
monitoring, and transaction data that may be reconstructed after the actual fact.
The 2026 Oxford–GlobeScan survey illustrates why this
issues past know-how groups: geoeconomic danger ranked first amongst
respondents at 76%, whereas AI and know-how danger rose from 17% in 2025 to 44%,
and governance reached 45% amongst ESG-related reputational considerations.
The Combat Beneath the Interface
The attention-grabbing battle won’t be between an app and an API.
It is going to be over what sits beneath each.
If an AI agent can select amongst monetary suppliers, the
suppliers greatest positioned to retain worth shall be those who nonetheless supply
one thing the agent can’t deal with as interchangeable: dependable market entry,
execution, regulated custody, financing, information, core know-how and supply
stack, or a mix of them.
On the finish of the day, the interface could or could not
basically change, and as soon as extra once more after that. The underlying take a look at is
whether or not the establishment stays helpful when the client now not has to
enter by means of its entrance door.