


Industrial actual property lenders face practically $1T in mortgage maturities over the following two years, and most of their credit score evaluation nonetheless occurs by hand. Every mortgage will get underwritten at origination, each quarter, at extension, and at refinancing, and each go begins with hire rolls, leases, and working statements that by no means share a format, so hiring extra analysts can not hold tempo. CarbonAI builds AI brokers that run that analytical work from underwriting and due diligence by funding memos and post-close surveillance. The brokers construction the messy paperwork, populate every lender’s personal fashions and memos, validate each determine in opposition to its supply, and route judgment calls to the lending staff. Early clients report chopping time on core underwriting duties by as a lot as 90%, and the corporate reached seven figures of ARR inside six months. As a result of the brokers log each motion, lenders can defend every quantity in entrance of credit score committees and regulators.
AlleyWatch sat down with CarbonAI Cofounders Jeff Saul (CEO) and Josh Kaufman (COO) to be taught extra concerning the enterprise, its future plans, current funding spherical, and far, way more…
Who had been your traders and the way a lot did you increase?
We’ve raised $12M in whole funding, led by Cowboy Ventures, with participation from Timber Grove Ventures, Bling Capital, and Max Ventures.
Inform us concerning the services or products that CarbonAI gives.
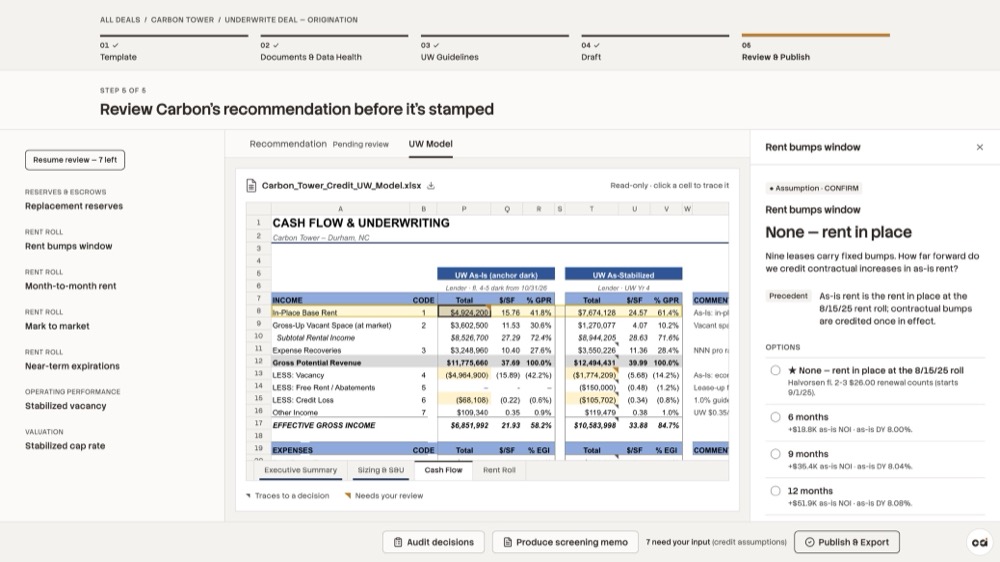
CarbonAI builds AI brokers for industrial actual property lending groups. Our brokers run the analytical work throughout the total lifetime of a mortgage, together with underwriting, due diligence, funding memos, and post-close surveillance. They begin by analyzing and structuring the messy, fragmented paperwork that underpin the mortgage, similar to hire rolls, leases, monetary statements, and mortgage paperwork. Then they run the workflow itself within the lenders personal distinctive fashions and memos: constructing the underwriting, drafting the memo, and flagging danger. Each determine is validated and traced again to its supply doc, and the brokers route the choices that want human judgment to the lending staff. After a mortgage closes, the identical brokers monitor the well being of the mortgage as new data is available in and current it within the lenders most popular codecs with full auditability. The result’s that you may make and handle extra loans with the identical staff and materially mitigate danger with greater constancy data and upleveling the place your staff spends their time.
What impressed the beginning of CarbonAI?
We each began our careers within the trenches of CRE finance. Josh was in underwriting and asset administration at Morgan Stanley, the place he spent hours of his day wrangling paperwork and triaging information simply to report on the well being of loans every quarter. Jeff spent years in lending and funding roles, most just lately at Starwood Capital, typically engaged on spreadsheets with no system to assist. We each lived the ache, and the degraded choices, that sluggish, messy legacy workflows bred.
We based Nativ, a CRE lending deal administration platform, and grew it to greater than 30 lenders and over $300B of AUM on the platform earlier than promoting it to Constructed. Even then, expertise may solely automate a small slice of the work. In 2024, as giant language fashions after which brokers turned highly effective sufficient to construction unstructured information and execute actual workflows, we noticed that the analyst work we used to do by hand may lastly be automated which birthed Carbon. It’s a pure evolution of our mission to make the capital underpinning our constructed world extra environment friendly and efficient. We perceive the issue house deeply each as practitioners and technologists and imagine that AI has the facility to rework this trade if correctly wielded.
How is CarbonAI completely different?
Most AI in our house is a chat device you immediate deal by deal. It makes errors you possibly can’t hint, and it doesn’t scale. Lenders don’t want that. They want brokers that already know the area and do the work reliably throughout the spectrum of offers that present up within the wild.
We all know as a result of we did this work ourselves as lenders. So Carbon is constructed the best way a seasoned underwriter thinks and operates. It takes the messy, non-conforming hire rolls, working statements, leases and mortgage docs our trade runs on, extracts and validates them, and flags something that doesn’t tie out. It learns and makes use of every agency’s personal lending parameters, fashions and studies, and will get sharper with each deal. And since we’ve sat by credit score committees and regulatory audits, each information level traces again to its supply and each agent motion is logged so that you at all times can audit proper again to the foundation supply.
The result’s certainty of execution at scale. Underwriters spend much less time triaging paperwork and extra time on the deal. Carbon is already doing this on actual offers for our clients.
What market does CarbonAI goal and the way large is it?
We serve industrial actual property lenders, from debt funds and mortgage REITs to company lenders, banks and publicly traded establishments. CRE is likely one of the largest asset lessons on the planet, roughly $20 trillion within the U.S. alone, and practically all of it’s nonetheless underwritten and monitored by hand. With practically $1 trillion of mortgage maturities coming due over the following two years and originations climbing, lenders must do extra with the groups they’ve however can not sacrifice high quality of the credit score evaluation.
What’s your enterprise mannequin?
Our pricing is outcome-based. For our extraction product, clients pay by the doc. For our brokers, they pay by the deal and mortgage stage, similar to finishing an underwriting, finishing due diligence, or finishing 1 / 4 of surveillance. There’s a small platform payment, however about 90% of our pricing is pushed by these outcomes and utilization.

How are you making ready for a possible financial slowdown?
Misery really will increase the necessity for what we do. Rising charges have lenders asking which loans of their books are strong and that are quietly deteriorating, and a slowdown solely sharpens that query. On our facet, we’ve been AI-native since day one, so we run lean and make investments rigorously. This funding goes largely to product and hiring.
What was the funding course of like?
Having raised and constructed earlier than, we went in understanding precisely what we wished: companions who perceive vertical AI and can stick with us for the lengthy haul, not simply the most important examine. Our traction allow us to run a centered course of and choose our companions. We’re thrilled Cowboy led, and it meant lots that current traders like Bling Capital, Timber Grove and Max Ventures doubled down. Then we acquired proper again to work!
What are the most important challenges that you just confronted whereas elevating capital?
The largest problem is that fundraising is a full-time job, particularly once you’re being choosy about strategic match, and it might simply pull you away from the enterprise. We’d been by it earlier than with Nativ, so we knew to guard in opposition to that. We’ve constructed a staff that actually owns the issue and the outcomes. Our job is to verify everyone seems to be aligned on the “what” and the “why”, then give them the belief and room to personal the ‘how.’ That’s what allow us to increase with out lacking a beat on product and clients.
What components about your enterprise led your traders to put in writing the examine?
Three core issues:
- First, the staff. Jeff and I spent years underwriting, closing and managing CRE loans at Starwood, Morgan Stanley and others. Then we constructed Nativ, which greater than 30 lenders adopted earlier than Constructed acquired it. Our traders had been backing individuals who’ve achieved the job and already constructed software program lenders belief.
- Second, traction. Whereas nonetheless in stealth, we crossed seven figures of ARR in six months, working with a number of the main gamers in CRE finance. Early clients have lower time on core underwriting duties by as a lot as 90%.
- Third, the scale of the issue. CRE lending is known as a labor downside, not a software program downside. A mortgage will get underwritten many times over its life: at origination, each quarter, at extensions and at refi. With the maturity wall hitting now, groups can’t rent their means by it. Carbon breaks the hyperlink between deal quantity and headcount, and each quantity traces again to its supply
What are the milestones you propose to attain within the subsequent six months?
It has by no means been extra complicated than now to purchase software program particularly for an trade with nuanced use instances that require actual speciality and rigor – We’re centered on serving to the CRE Finance neighborhood make sense of this AI puzzle and evolve their working fashions for an AI native future that has already manifested in adjoining sectors like legislation and accounting.
To perform this we will probably be:
- Partnering with a number of the most essential lenders within the house on remodeling their working mannequin
- Rising the staff to proceed increase our expertise density throughout our technical workers, and our GTM operate
Working with key trade commerce organizations to make expertise a first-class citizen within the agenda. Will proceed partnering carefully with organizations like CREFC, Mortgage Bankers Affiliation and others to create productive collaboration and discourse. We’ll have an enormous presence on the CRE Finance Council convention in Miami in January.
What recommendation are you able to provide firms in New York that shouldn’t have a recent injection of capital within the financial institution?
Perceive your clients deeply. There isn’t any substitute for taking a second to maneuver off the answer and perceive the workflow, ache factors, outcomes and penalties of the area you propose to enhance. Then be sure you absolutely admire the nuance in implementing that answer and architect a course of for it that units everybody up for achievement.
Lastly, it’s by no means been a greater time to be constructing. Method issues first ideas with the brand new AI instruments that we now have at our disposal and reimagine your personal operations to run leaner and more practical. We’ve been AI-native from the beginning, and it lets a small staff do excess of it may a number of years in the past.
The place do you see the corporate going now over the close to time period?
Our aim is to automate CRE investing by 2030. Within the close to time period, which means turning into the system of motion for lending groups, sitting on prime of their current techniques and working the analytical work from underwriting by post-close surveillance. Long run, we see a totally AI-native deal lifecycle, the place groups spend their time on judgment calls as a substitute of administration. That issues past anybody agency. Housing, information facilities, and power infrastructure all rely on capital flowing into actual property, and sluggish, handbook lending is friction that holds it again.

You might be seconds away from signing up for the most well liked record in NYC Tech!
Join right now