JLGutierrez/iStock through Getty Pictures
The S&P 500 is buying and selling at 18.8X ahead earnings and 26.15X trailing earnings. By each measures, it is nicely above historic norms. Its true valuation is even greater as earnings are being artificially inflated by the delta in timing recognition of earnings vs. bills associated to AI capex. In short, earnings are being totally acknowledged in 12 months 0, whereas solely a fraction of bills are hitting the revenue assertion.
Historic valuation
Yardeni Analysis exhibits S&P 500 ahead multiples at 18.8X. Observe on the graph beneath that valuations solely acquired this excessive briefly in the course of the pandemic (on account of earnings dropping) and in the course of the dot-com bubble.
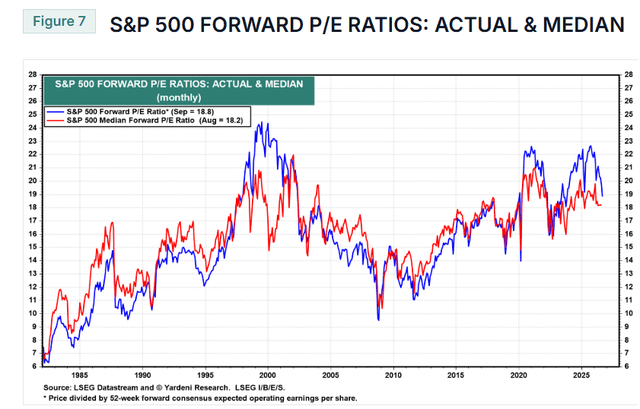
Yardeni
Trailing valuation exhibits the same story, with the 26.15X trailing a number of solely surpassed by three time intervals:
- Pandemic earnings crash (low earnings = excessive a number of).
- Dot-com bubble (outrageous valuation).
- 2008 Nice Monetary Disaster (low earnings).
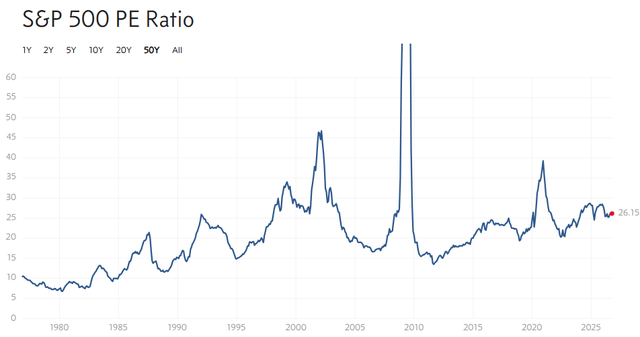
multpl.com
This excessive valuation in 2008-2009 didn’t present up within the graph of the ahead a number of as a result of earnings estimates remained optimistic at the moment. It exhibits up within the trailing a number of as a result of precise earnings cratered in the course of the disaster.
Whereas present multiples are excessive, I posit that they are truly considerably greater if one adjusts for the distortion ensuing from depreciation schedules.
S&P 500 Earnings Breakdown
In line with Morningstar, the S&P constituent complete market cap is $65.93 trillion. Thus, the 18.8 ahead a number of implies ahead earnings of $3.5T.
Of that $3.5T, about $577.7B comes from chip and reminiscence corporations.

2MC
That represents about 16.5% of general S&P 500 earnings.

2MC
These earnings are totally respectable. Some could argue that corporations like Micron (MU) or Nvidia (NVDA) are at cyclical highs and will come again down a bit, however the earnings they’re pulling in right this moment are actual. It is precise money move coming in.
So I don’t have a gripe with that contribution to earnings. As a substitute, my gripe is that the associated fee aspect of it isn’t being mirrored in bills of S&P 500 corporations.
Chip and reminiscence corporations are excessive margin, however revenues are nonetheless considerably greater than earnings. These within the S&P 500 have anticipated 2027 revenues of $1.091T.
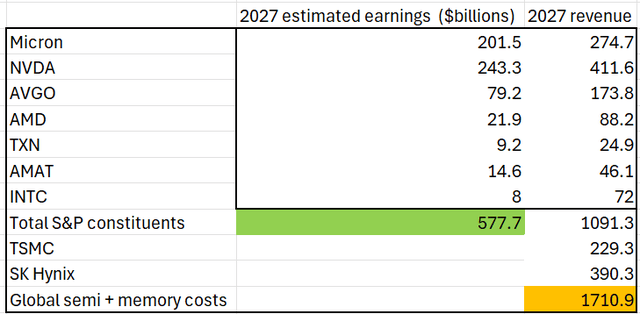
2MC
Inclusive of TSMC and SK Hynix, chip and reminiscence revenues are anticipated to achieve $1.71T in 2027.
The shoppers shopping for from these chip and reminiscence corporations are overwhelmingly constituents of the S&P 500. Thus, a good portion of the $1.7T is an expense line for the S&P 500.
Or somewhat, it must be.
Depreciation schedules are stopping that value from exhibiting up in actual time.
S&P firm bills on Chips and Reminiscence
Most S&P corporations don’t instantly break down the portion of their bills coming from chips and reminiscence. They’re bucketed into line objects like capex. So we can’t get a precise determine. As a substitute, we are going to try to calculate it from the gross sales of chips and semi-companies to S&P corporations.
Allow us to start by estimating the portion of chip and reminiscence revenues that come from S&P 500 prospects.
NVDA’s 10-Okay reveals that 61% of its gross sales are to prospects A, B, C, and D.
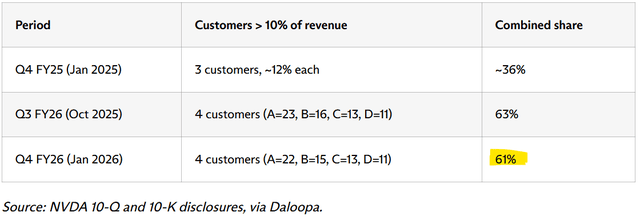
NVDA and Daloopa
Whereas listed anonymously, prospects A, B, C, and D are regarded as some mixture of Microsoft (MSFT), Meta (META), Amazon (AMZN), and Google (GOOG) (GOOGL).
These are all S&P 500 corporations.
Subsequently, not less than 61% (in all probability considerably greater) of NVDA’s revenues are an expense merchandise for the S&P.
If we apply this identical 61% determine throughout the trade, that is complete gross sales to S&P 500 corporations of $1.04T.

2MC
The 61% determine as a share of gross sales to S&P corporations is low for NVDA however could be barely excessive for abroad gamers like SK Hynix. General, I believe it is in the fitting ballpark however clearly with vital error bars in each instructions.
Utilizing this determine, we will estimate the distortion attributable to accounting elections.
Depreciation Schedule Distorting Earnings
- Earnings of $577.7B attributable to S&P 500 corporations in 2027 are forecast to return from chip and reminiscence corporations.
- Bills associated to chips and reminiscence of S&P 500 corporations in 2027 are roughly $1.04T.
This is the imbalance: Everything of these estimated earnings are being counted towards S&P 500 2027 earnings, whereas solely a fraction of the expense is being recorded in 2027.
The fraction of expense is unusually low as a result of depreciation schedules of the hyperscalers have been lengthened.
- In 2023 Alphabet lengthened its depreciation schedule from 4-5 years to 6 years. The brand new longer determine exhibits up within the fiscal 2024 10-Okay.
“We depreciate servers and community tools typically over a interval of six years.”
- In 2025, Meta prolonged depreciation schedules from 4-5 years to five.5 years as per the 10-Okay.
“In January 2025, we accomplished an evaluation of the helpful lives of property and tools, which resulted in a rise within the estimated helpful lives of most servers and community belongings to five.5 years.”
Which means these corporations are solely expensing about 18% of their chip and reminiscence expense within the 12 months during which they purchase it.
- ~$1.04T will likely be spent on chips and reminiscence in 2027.
- ~$190B of that $1.04T will likely be expensed in 2027.
The remaining stays on their steadiness sheets as a depreciable asset.
This creates an $854B hole between the money S&P 500 corporations are paying versus what is definitely exhibiting up as bills.

2MC
Depreciation expense schedules do catch up over time, as this expense merchandise will likely be recurring for the subsequent 5.5 to six years, however due to how quickly capex has accelerated, the cumulative depreciation is way behind the money outlay.
Because of this, AI-related bills are being drastically understated on revenue statements in 2026 and 2027.
What does this imply for general earnings and valuation?
Making use of the numbers to valuation
If the S&P 500 corporations had been to deal with your entire $1.04T money spent on chips and reminiscence as a real expense somewhat than depreciating it over freshly lengthened depreciation schedules, S&P 500 earnings could be decrease by about $854 billion.
That is totally 24% of the $3.5T S&P corporations are forecast to earn in 2027.
Multiples already look excessive for the index, and earnings are being overstated by $854B. If one considers money expense to be an actual expense, the ahead a number of of the S&P 500 could be 24.8X
The forecast ahead a number of of 18.8X for the S&P 500 is already fairly excessive by historic requirements. 24.8X adjusted multiples are astronomically excessive and, in my view, bubble territory.
The underside line
Over time, as there have been extra years of exceedingly excessive capex, depreciation will begin to catch up. Because it does, it’ll take an enormous chew out of earnings development.
The web impact of the timing of expense recognition in these depreciation schedules is that it has pulled ahead future earnings. In 2028, 2029, and 2030, these corporations will nonetheless be expensing their 2026 and 2027 capex.
As the complete expense begins to be acknowledged, earnings will look far weaker than the market is pricing in.